Plan strategically. Apply confidently. Pay wisely. Save intentionally.
You've built wealth and raised a high achiever. The Four Pillar Plan makes sure the college decision builds your student's future without draining your family's.
If you earn over $150K, you've been told not to bother. So most families don't plan. They just pay.
Merit scholarships have nothing to do with income. Families who assume they won't qualify leave $40K–$120K on the table.
The school your student wants and the school that will reward them financially are often different. Fit changes the outcome.
Merit positioning, FAFSA strategy and asset decisions happen years before applications. Planning should start in 9th grade.
One plan that connects the future, the application and the money.
Most advisors cover admissions or finance. Every family we work with gets all four pillars, in order.
What happens in 30 minutes.
Your student's grade, goals, schools of interest and your family's financial picture.
Where merit aid, financial aid and savings are realistically available to you.
Clear next steps across the four pillars, whether you work with us or not.
I sit where admissions and finance meet. That's where your family's money is.
I'm Stephanie Gibbs, a Certified College Planning Strategist, financial planner, high school and dual enrollment counselor, and NIL educator. I'm the CEO of College Planning Professionals and Sharkey Financial.
Based in Rancho Cucamonga, I work with families across the Inland Empire, Orange, Riverside and Los Angeles counties, and virtually nationwide.
Schedule a free strategy call →Results that pay for themselves.
"We thought we made too much to get any aid. Stephanie built a college list where our daughter received $68,000 in merit aid from her first-choice school."
"The award letter negotiation alone paid for Stephanie's services five times over. Most families just accept the first offer."
"Our son is a recruited athlete and we had no idea how NIL would affect his aid. Stephanie walked us through every piece of it. A game changer."
Start learning.
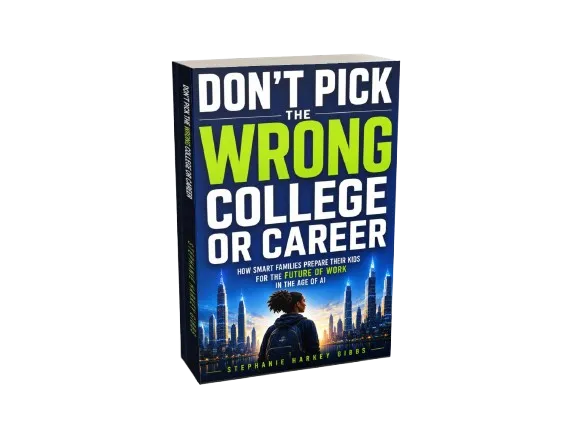
How AI, rising costs and career change connect, so you choose a path with less regret.
Buy the book →Live training for parents and students. Seats are limited.
Register now →Merit aid, award letters, dual enrollment, NIL and AI-powered planning.
Subscribe on YouTube →Questions families ask
Can high-income families qualify for college aid?+
Yes. Merit scholarships are separate from income. Many private colleges award $20,000–$80,000+ a year in merit aid. The key is a college list where your student is in the top 25% academically.
How is this different from a school counselor?+
School counselors manage hundreds of students and rarely have time for individual financial strategy. We combine admissions strategy and financial planning in one plan for your family.
When should we start?+
Ideally by 9th grade, when course selection, dual enrollment and asset strategy can still be set up. Families starting in 11th or 12th grade still benefit.
Can we negotiate an award letter?+
Yes, and most families never try. A well-documented Professional Judgment Appeal, timed correctly, can add thousands to tens of thousands in aid.
How does NIL affect financial aid?+
NIL income counts as student income on the FAFSA. How it interacts with athletic and institutional aid is school-specific, so structuring it correctly protects both.
Do you work with families outside Southern California?+
Yes. Strategy sessions, list reviews, award negotiations and NIL planning all work virtually, nationwide.
Your student's future is worth
a 30-minute call.
We'll map where you stand on all four pillars and where the money is.
Book a Free Strategy CallPrefer to talk now? Call (909) 210-7049